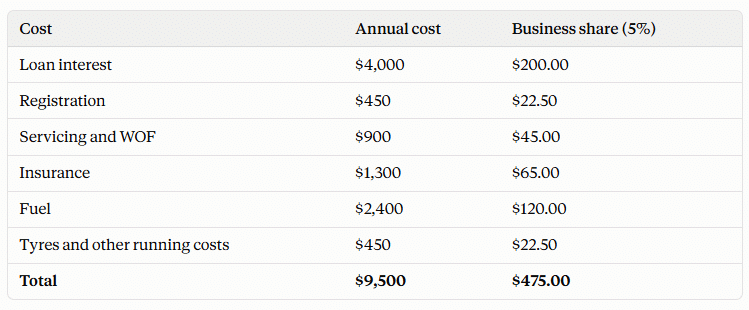Motor vehicle FBT changes you say? Yes. The New Zealand Government has confirmed the most significant overhaul of the motor vehicle Fringe Benefit Tax (FBT) rules in decades. From 1 April 2027, employers will no longer calculate FBT primarily by counting the days a vehicle is available for private use. Instead, they will classify vehicles into categories(opens in new tab) based on how employees use them in practice.
NB: Updated 25 October 2026. This was to reflect the Taxation (Annual Rates for 2026–27, FBT Simplification, Foreign Investment Funds, and Remedial Measures) Bill. It was introduced to Parliament on 10 September 2026. The Bill confirmed several details not yet settled when this article was first published in June. Information provided by IRD and analysis since then has provided additional clarification. As of October 2026, we await the closing date for submissions, which will be set after the November election. (In other words, this is not set in stone so there may be further changes). The Bill will be enacted by 31 March 2027.
Key Points Summary
For many businesses, the new rules will simplify compliance. However, they will also create clear winners and losers. The Government is removing long-standing concessions for work-related vehicles, particularly sign-written double-cab utes. In contrast, some businesses that currently pay high levels of FBT on branded vehicles used mainly for business could significantly reduce their FBT liability.
So In Simple Terms…?
The key message for business owners is simple: the type of vehicle will matter less, while the way employees use the vehicle will matter much more. (Note that this blog post doesn’t discuss the new Investment Boost provision. See here for more info).
Why Are the Rules Changing?
The current FBT regime focuses on whether a vehicle is available for private use. Even if private use is minimal, FBT can still arise if the vehicle is made available to an employee. Businesses often need to track exempt days, maintain detailed records, and monitor restrictions on private use throughout the year.
The Government has acknowledged that the rules have become complicated and can produce inconsistent outcomes. Under the new framework, Inland Revenue intends to focus on the level of private benefit being provided rather than simply whether a vehicle happens to be available for private use on a particular day.
Create a more consistent framework across different vehicle types.
The FBT motor vehicle weight threshold is also rising, from 3,500kg to 6,000kg — bringing heavier utes and SUVs (including models like the Ford Ranger Super Duty) within the same category framework, reflecting how much heavier many modern utes and EVs have become since the current threshold was set.
When Will the Changes Apply?
The Taxation (Annual Rates for 2026–27, FBT Simplification, Foreign Investment Funds, and Remedial Measures) Bill was introduced to Parliament on 10 September 2026. The finer details may still change. New rules are set to apply from 1 April 2027.
Therefore, businesses with vehicle fleets should start reviewing their arrangements well before the commencement date.
The Big Shift: From Availability to Vehicle Categories
Currently, motor vehicle FBT is generally triggered when a vehicle is available for private use. The extent of actual private use is often secondary to the vehicle’s availability. Under the new regime, vehicles will instead be classified into categories that reflect their primary use. This means the central question will become:
How is the vehicle used?
Pick the category once, based on expected use.
Back it up with a clear policy and a signed employment agreement.
Ignore the odd weekend loan.
Revisit the category only when use genuinely changes, and the new one starts next quarter.
The daily day-counting and logbooks disappear, but the evidence requirement doesn’t. The work shifts from tracking to classifying correctly.
The New FBT Formula
The formula is cost or tax book value × valuation rate × category percentage × FBT rate. The valuation rate comes first. The category percentage then reflects the private benefit.
Instead of adjusting for exempt days, the calculation will use an inclusion rate based on the vehicle category. The inclusion percentage is effectively Inland Revenue’s estimate of the amount of private benefit provided. This change removes the need to calculate exempt days throughout the year for many vehicles.
Tax Book Value Method (if Investment Boost claimed)
Petrol/Diesel: 41.4%
Hybrid: 40.52%
Electric Vehicle: 35%
Tax Book Value Method (if Investment Boost not claimed)
Petrol/Diesel: 36%
Hybrid: 34.12%
Electric Vehicle: 29.76%
The lower rates for hybrids and EVs reflect their generally lower operating costs. These rates are proposed to be reviewed every four years.
Understanding the New Categories
The Bill sets out six categories:
Full private use – 100%
Partial private use – 35%
Limited private use farm vehicles – 35%
Minor private use – 20%
Multi-worksite vehicles – 0%
Pool vehicles – 0%
Category 3 covers farm vehicles; number 4 covers commuting to a single worksite. Category number 5 covers commuting between multiple worksites. Lastly, Category 6 covers pool vehicles. Pool vehicles don’t need branding.
Category 1 – Full Private Use (100%)
Category 1 applies where the vehicle is mainly used for private purposes. These are the traditional company vehicles provided as employee perks and often form part of remuneration packages. Private use is broadly unrestricted. This is also the default category — if an employer doesn’t select an appropriate category for a vehicle, it defaults here.
A company supplies a manager with a vehicle that can be used freely:
Personal shopping
School runs
Holidays
Weekend trips
The vehicle is primarily a personal benefit. Under the new regime, the vehicle will generally fall into Category 1 and attract a 100% inclusion rate. For some businesses this may produce a worse result than the current rules, particularly where they previously relied on exempt-day calculations.
The LTC purchases a vehicle. It is occasionally used to visit the rental property but is used mostly for personal things. Owners (i.e. shareholders) aren’t employees under the LTC rules so no FBT applies. Instead, the private-use costs become non-deductible.
Worked Example: Leah and Craig’s LTC Buys a $50,000 SUV
Leah and Craig each hold 50 of the 100 shares in an LTC. Both are directors. The LTC owns residential rental properties and nothing else. Property managers handle the tenants, inspections and repairs.
The LTC buys an SUV for $50,000 with a bank loan. The LTC isn’t GST-registered, because GST isn’t charged on residential rent. So every figure below includes GST.
Leah and Craig drive the SUV 15,000 km a year. They use it for family trips and everyday errands. Craig occasionally drives out to a rental to check on a repair. They keep a logbook for 90 days. It shows 5% business use, or about 750 km a year.
Does FBT apply? No. Neither owner is an employee of the LTC. They have no employment contracts. FBT applies to benefits provided to employees. The new FBT categories don’t apply either. The tax cost is lost deductions, not FBT.
The LTC’s costs for the year are:
The example ignores depreciation, which follows the same apportionment.
The LTC passes the $475 through to its owners in proportion to their shares. Leah and Craig each claim $237.50. At a 33% marginal rate, each saves about $78. That is about $157 in total.
The remaining $9,025 is private use and isn’t deductible. The LTC doesn’t claim it.
What happens to the private share? IRD treats a benefit an LTC provides to a shareholder as a distribution of profit, not a business expense. If the LTC deducted it, every owner would get a deduction for the owners’ private benefit. Leah and Craig use the SUV equally. So each is treated as receiving a distribution of half the private cost, $4,512.50 ($9,025 ÷ 2). The LTC doesn’t deduct any of it.
Suppose the LTC claims all $9,500 instead. Each owner claims $4,750 and saves about $1,568 at 33%. That overclaims about $2,978 of tax. IRD can reverse the claim and may charge interest and penalties. Without a logbook, IRD caps the claim at 25% of running costs. A logbook proves the real percentage.
The lesson: Owning the SUV through the LTC doesn’t create deductions. With 5% business use, the LTC can only claim about $475 of $9,500 in costs.
This category is likely to be one of the most important for many businesses. The vehicle must:
Be mainly used for business.
Be branded, subject to express exceptions
Allow regular commuting.
Allow private use during rostered days off, leave periods, public holidays.
Example 1 – Consulting Business
A consulting firm provides a sign-written vehicle that staff use to visit clients every day.
The vehicle:
Goes home with the employee.
Is used extensively for business.
May be used privately during weekends and holidays.
Under current rules, FBT may be close to 100%. Under Category 2, only 35% of the vehicle value is subject to FBT.
Example 2 – Tradie Vehicle
A sign-written hatchback is driven between jobs during the day and taken home at night. Although not a ute and not previously qualifying as a work-related vehicle, it may qualify for Category 2 if it is mainly used for business. This could significantly reduce FBT compared with current outcomes. For many businesses this category will represent a genuine tax saving.
What “Branded” Actually Means
Branding isn’t just a nice-to-have for Categories 2, 4, and 5 — it’s a defined legal test (proposed section CX 36B), and it’s stricter than many businesses might assume. To qualify, identification on the vehicle must be:
Prominent — visible on the vehicle’s exterior.
Permanent — the same form of identification the business regularly uses in its operations
The identification regularly used by the Employer i.e. the logo, not just a business name.
This matters in practice: removable magnetic signage won’t qualify, since it can be taken off for private use. A vehicle marketed as “branded” but not genuinely and permanently marked defaults to Category 1 — the 100% inclusion rate — regardless of how restricted its actual private use is.
Proposed exemptions
Three carve-outs may soften this for some:
Farming businesses that aren’t widely-held companies are exempt from branding altogether.
A Commissioner-approved exemption is available on application where branding isn’t appropriate. For example, this could be for sensitive business or security-related roles, or an unmarked vehicle used for safety-sensitive work.
Branding is not required for vehicles bought or leased before 10 September 2026.
The Biggest Loser: Work-related Vehicles
The headline change is the repeal of the traditional work-related vehicle exemption. Historically, many businesses have relied on the exemption for:
Double-cab utes.
Vans.
Other qualifying work-related vehicles.
Where private use was restricted, FBT could often be reduced to nil. Those rules are effectively disappearing. Alongside the work-related vehicle exemption, the emergency call and business travel exemptions are also being removed — they’re no longer needed under the category approach. The on-premises exemption is being retained, and a new exemption is being introduced specifically for emergency services vehicles.
Example
A sign-written double-cab ute used by a building company.
Current rules:
Home-to-work travel only.
Restricted private use.
Often 0% FBT.
New rules:
Weekend and holiday use allowed: Category 2 (35%).
Commuting only, one regular worksite: Category 4 (20%).
Commuting only, several worksites: Category 5 (0%).
Unrestricted private use, or no branding on a vehicle acquired after 10 September 2026: Category 1 (100%).
Result: Some utes currently at nil FBT will move to 20% or 35%. Others may stay at 0%. The outcome turns on use and branding, not the vehicle type.
This is why many tax advisers describe ute owners as the major losers under the reforms.
Category 3 – Farm Vehicles (35%)
This category specifically addresses farming businesses.
The vehicle must:
Be mainly used for farming activities.
Be owned by a closely-held farming company or employees / beneficiaries of closely-held farming companies or family trusts.
Be used by a shareholder-employee.
Support farming operations.
Unlike Category 2, branding is not required. Regular commuting and private use on non-workdays is allowed.
Example
A dairy farming company owns a utility vehicle used throughout the farm. If the vehicle is mainly used for farming operations, it may qualify for Category 3 with a 35% inclusion rate. For many farming businesses this will be a favourable outcome compared with current non-WRV situations.
Category 4 – Minor Private Use (20%)
Category 4 is designed for vehicles that are primarily business vehicles but allow limited private use. It covers an employee who commutes to the same single worksite.
Requirements include:
Vehicle mainly used for business.
Branded vehicle.
The only private use is commuting by the same employee to the same worksite.
No private use on non-working days.
Example
An electrician drives a sign-written van:
Home to work.
Work to customer sites.
No private weekend use.
The vehicle may qualify for Category 4. Only 20% of the vehicle value is subject to FBT. For businesses currently paying substantial FBT on non-WRV vehicles, this category could produce a significant saving. Note that Category 4 vehicles can be used for business by other staff at work
Category 5 – Multi-Worksite Vehicles (0%)
Category 5 is potentially the most favourable category. It covers an employee who commutes from home to work that requires travel across several worksites, or a project of limited duration.
It applies when:
The vehicle is used for business.
The employee travels across multiple worksites.
Private use is limited to commuting associated with those work patterns.
Branding requirements are met.
Category 5 vehicles can be used for business by other staff at work. In practice, an employee takes the vehicle home and commutes in it. Colleagues can still use it for business during the day without changing its category. (A pool vehicle – Category 6 – is different because it isn’t allocated to one person).
Example 1 – Plumber
A plumber leaves home each morning and travels directly to various client sites. The vehicle is genuinely required for multiple worksites. The inclusion rate may be 0%.
Example 2 – Service Technician
A technician attends five different customer locations daily. Under current rules the employer may have FBT exposure. Under Category 5 there may be no FBT liability at all. This category could become one of the most important planning opportunities under the new rules.
Category 6 – Pool Vehicles (0%)
Pool vehicles continue to receive favourable treatment.
Vehicles can qualify where they:
Are exclusively business vehicles.
Are available to multiple employees.
Are not assigned permanently to one person.
Have no private use other than incidental i.e. no regular commuting from home to work is permitted.
Example
A business maintains three vehicles at its premises. Any staff member can use them during work hours, but nobody regularly takes them home. The vehicles may qualify for a 0% inclusion rate. However, the rules appear stricter than current arrangements, with very limited scope for occasional take-home use.
Rental and Hire Vehicles Are Treated Differently
Rental car and campervan operators don’t sort vehicles hired out to the public into the category system at all — those vehicles are instead treated as unclassified benefits. This avoids an unintended over-taxation result that the weight threshold increase would otherwise create for hire fleets.
An Alternative for Small Companies
If your close company provides no more than two vehicles, and treats both as unclassified benefits, you may be able to elect into the existing subpart DE motor vehicle expenditure rules instead of the new category system entirely. This is worth discussing directly if
you run a small LTC or company with just one or two vehicles,
the company’s sole employee benefits are unclassified benefits
Will Logbooks Still Be Required?
No. Employers choose a category based on the vehicle’s expected use when it is first provided. Policies and employment agreements support that choice. Incidental private use, such as a one-off weekend loan, is ignored. Reclassification is only needed when expected use changes materially. The new category then applies from the next quarter.
That being said, close-company shareholder-employees can still choose the logbook method for new vehicles. The conditions are no more than two vehicles and no other benefits, and they can’t switch back to FBT.
The reforms remove day-counting and detailed logbooks.
Employers still need records that support their category.
The compliance work shifts from daily tracking to getting the classification right.
The compliance burden therefore does reduce but does not disappear entirely.
What Businesses Should Be Doing Now
Although implementation is still some time away, businesses should start reviewing vehicle arrangements. Key actions include:
Review Fleet Usage
Assess how employees (or shareholders) use each vehicle in practice and determine which category best reflects that use.
Check Branding
Several categories require branding, and the definition is stricter than many expect — removable signage won’t qualify. A branded vehicle may qualify for significantly lower inclusion rates than an unbranded vehicle, but only if it meets the prominent-and-permanent test.
Identify Work-Related Vehicle Exposure
Businesses heavily reliant on current work-related vehicle exemptions should calculate likely future costs now.
Consider Vehicle Allocation Policies
Pool vehicles and multi-worksite vehicles may become more attractive from an FBT perspective.
Consider the Small Company Alternative
If you run two or fewer vehicles through a close company, check whether electing into subpart DE instead of the category system suits you better.
Note: This applies only where the company’s sole employee benefits are unclassified benefits and no more than two vehicles are involved.
Monitor Legislative Developments
As of October 2026, the Bill is with the Finance and Expenditure Committee. Submissions are encouraged by 1 December 2026. Select committee is expected to report by February 2027. The general election adds uncertainty, because the next Government must decide whether to reinstate the Bill. The detail may still change.
Final Thoughts
The motor vehicle FBT reforms will deliver the biggest change to New Zealand’s vehicle taxation rules in more than 40 years. Inland Revenue will replace technical availability tests and exempt-day calculations with a category-based framework that focuses on how businesses and employees actually use vehicles.
Many businesses, particularly those that operate branded vehicles primarily for business purposes, should benefit from lower FBT costs and simpler administration. However, owners of traditional work-related vehicles and double-cab utes may face significantly higher tax bills under the new rules.
Businesses that act early will put themselves in the strongest position. By understanding the new categories, checking whether the branding requirement genuinely applies to their vehicles, reviewing fleet structures before 1 April 2027, and aligning vehicle-use policies with the appropriate category, they can better manage future FBT costs and compliance obligations. As always, the detail will be critical. Accountants, business owners, farmers, and fleet managers should pay close attention to the Bill’s progress through select committee to understand exactly how the new rules will apply.